For senior couples considering marriage later in life, the excitement of committing to a golden years partnership often sits right beside practical worries that can’t be brushed aside. Aging and remarriage can bring late-life relationship challenges that younger couples rarely face, especially when combining households, routines, and long-held expectations. The core tension is simple: building a shared life should feel secure and respectful, yet one misstep can create stress with money, family, or future care. With the right clarity up front, senior couples can move forward with confidence and shared peace of mind.
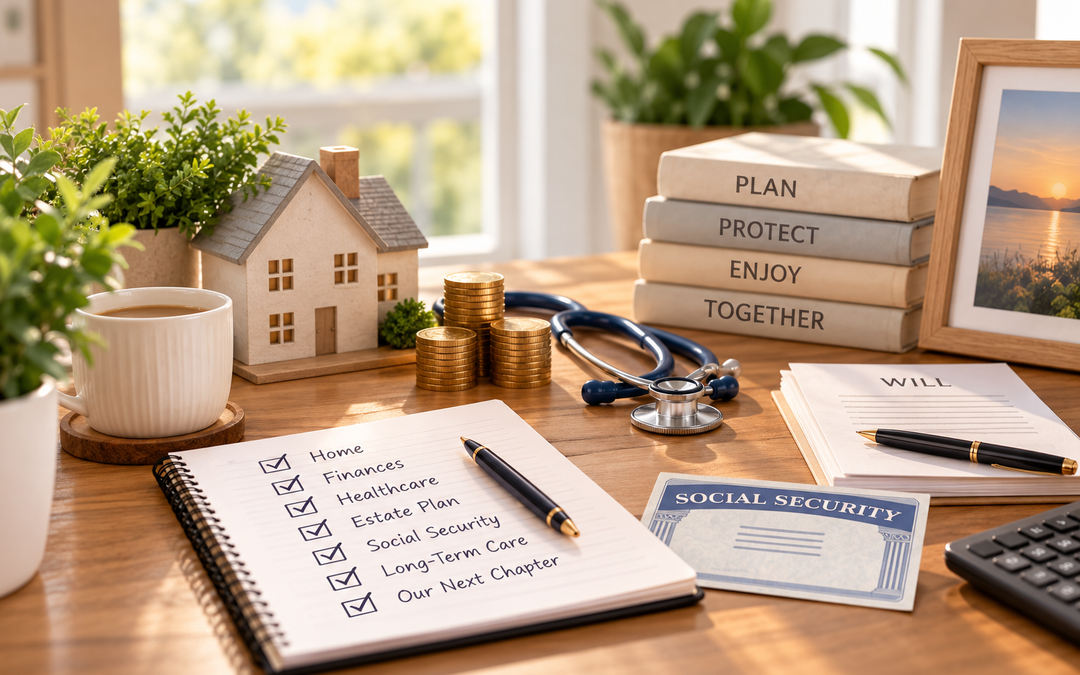
Build Your Shared Life Plan, Step by Step
This process helps you combine a home, money, benefits, and future-care decisions in a calm, orderly way. It matters because small oversights in later-life marriage can trigger big hassles with bills, coverage, or family expectations.
Choose the right home base
Start with a simple decision: one home, two homes, or a new place together, then list what must be true for it to work (safety, stairs, proximity to care, room for visitors, and budget). Decide what each person brings into the household and what stays separate, especially sentimental items. Getting the living setup right reduces daily friction and sets the tone for teamwork.
Merge finances with clear rules
Make a shared snapshot of income, debts, monthly bills, and account ownership, then agree on a system (one joint checking for household costs plus personal accounts is common). Choose who pays which bills, how you reimburse each other, and how you will handle surprises. Put the agreement in writing so it feels fair and stays clear when stress is high.
Coordinate Medicare and other insurance
Compare each person’s current coverage and doctors, then call the plan providers to confirm what changes with marriage, moving, or adding a spouse. Double-check prescriptions, out-of-network rules, and whether you need supplemental coverage so you are not paying twice for the same protection. Treat this step like a safety check before you combine day-to-day life.
Update your estate plan and beneficiaries
Schedule time to update wills, powers of attorney, health care directives, and beneficiary forms for retirement accounts and life insurance. Decide what you want to happen if one of you becomes unable to make decisions, and how you want to provide for adult children or other family members. This is how you protect each other while also preventing confusion later.
Review Social Security and start long-term care planning
Ask the Social Security Administration how marriage affects your claiming strategy and survivor benefits, and keep your budget flexible since Social Security benefits change over time. Then begin a long-term care conversation now, because 69% of people will use long-term care services at some point. Decide who you would call first, where you would want help to happen, and how you might pay for it.
Build a Small Business Together
Once you’ve aligned your home, money, and paperwork, you may find you also want a shared project that brings in income and purpose. To start a small business together, begin with a simple idea you both enjoy, then pick an easy business structure (many couples choose an LLC). Next, talk through who does what, day-to-day operations, customer work, and basic recordkeeping, so expectations stay clear. After that, handle the formation filings carefully and set up the basics you’ll rely on, like a simple website and a straightforward way to track money. An all-in-one platform like ZenBusiness can help you form an LLC, manage compliance, create a website, or handle finances.
Weekly Habits That Keep Love and Money Steady
Big decisions matter, but steady routines are what make later-life partnership feel safe day after day. These habits keep communication clear, reduce money surprises, and protect your time for the parts of retirement you actually want to enjoy.
Ten-Minute Sunday Check-In
- What it is: Share one win, one worry, and one request for the week.
- How often: Weekly
- Why it helps: Small concerns get handled before they become big arguments.
Friday Money Snapshot
- What it is: Review spending, upcoming bills, and any medical costs together.
- How often: Weekly
- Why it helps: Budgeting feels less scary when you both see the same numbers.
Quarterly Asset Inventory
- What it is: Use a simple list to take stock of assets and update balances.
- How often: Quarterly
- Why it helps: You catch gaps early and make calmer decisions.
Daily Health Cost Note
- What it is: Track prescriptions, copays, and appointments since one-third of healthcare expenses can be yours.
- How often: Daily
- Why it helps: Healthcare stays predictable, not a monthly surprise.
Shared Hobby Appointment
- What it is: Put one enjoyable activity on the calendar and protect it.
- How often: Weekly
- Why it helps: Fun creates connection when life feels routine.
Remarriage Questions Seniors Ask Most
Q: What happens to Medicare if we get married?
A: Medicare itself does not go away when you marry, but premiums and extra assistance programs can change based on household income. If either of you receives Medicaid, Medicare Savings Programs, or Part D Extra Help, report the marriage quickly to avoid surprise bills. A quick call to Medicare and your state benefits office can prevent gaps.
Q: How does our tax filing status change after marriage?
A: You will generally file Married Filing Jointly or Married Filing Separately starting the year you marry. Joint filing can simplify paperwork and may lower taxes for some couples, but it can also raise taxes if one of you has large deductions or certain benefits. Ask a tax pro to run both scenarios before year-end.
Q: Should we update our wills and beneficiaries right away?
A: Yes. Since estate planning covers what happens to assets if you die or become incapacitated, it should match your new household and any adult children. Update beneficiaries on retirement accounts and insurance first, then revise wills, powers of attorney, and health directives.
Q: When can I claim Social Security spousal benefits after remarriage?
A: Spousal benefits depend on age, work record, and the length of the marriage, so timing matters. Bring both of your earnings histories to the Social Security office or use their estimator to compare options. If either of you was widowed or divorced, confirm how remarriage affects those benefits before you file.
Q: How should we plan for long-term care costs together?
A: Build a shared estimate early because care can be expensive and inflation sensitive. The nursing home cost 20 years projection shows how quickly the numbers can climb, so consider setting savings targets and discussing insurance or a care plan with family. Put the plan in writing so neither of you is guessing later.
Start Calmly: One Thoughtful Step Toward a Secure Senior Partnership
Late-life marriage can feel like a balancing act: protecting benefits and family plans while still opening your heart to a new partnership. The steadier path is a simple mindset, combining lives thoughtfully, using future planning for seniors as the guide, and keeping a positive outlook on remarriage without rushing decisions. When couples work this way, money conversations get clearer, boundaries get kinder, and building secure retirement relationships starts to feel manageable instead of stressful. Move slowly, plan clearly, and let commitment follow readiness.